This case reads corporate failure as a system of reporting, governance, capital structure, creditor position, legal process and stakeholder consequence — not a single headline or hindsight story.
Casebook / 05
Steinhoff: governance, debt & dissolution.
A collapse is not explained by one disclosure alone.
What combination of reporting, debt, governance and legal pressure turned warning signals into corporate collapse?
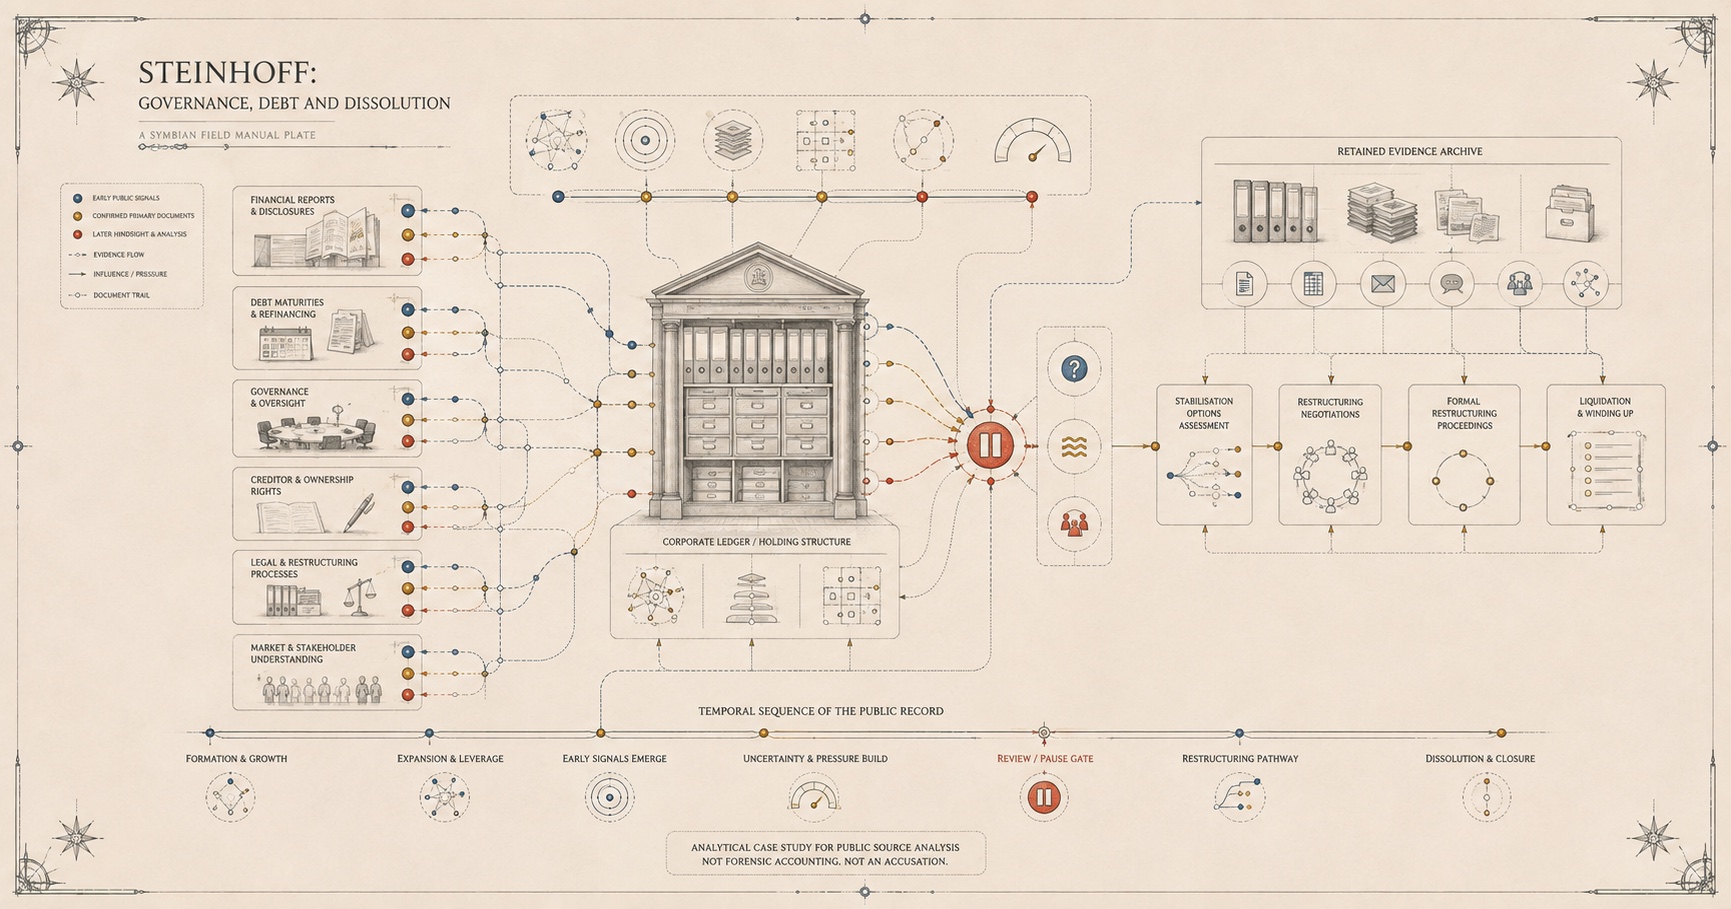
This page demonstrates a way of structuring inquiry. It does not constitute professional advice, verified intelligence, a recommendation or a conclusion about any person, organisation or transaction.
Visual field plates
Make the field visible.
Keep the claim bounded.
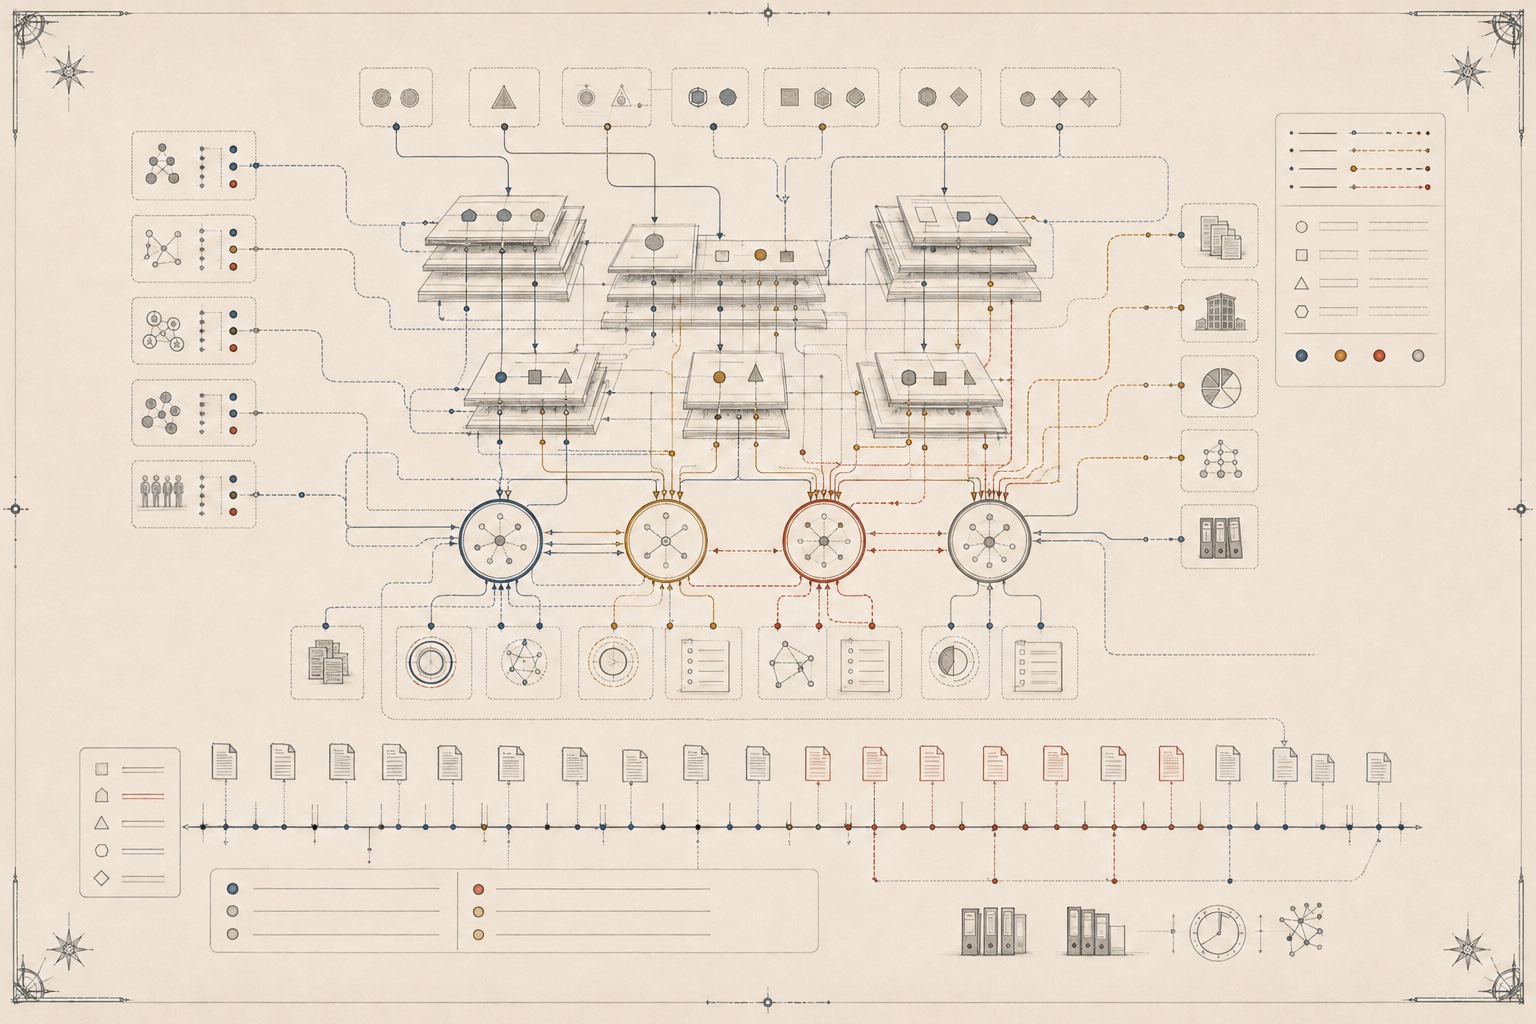
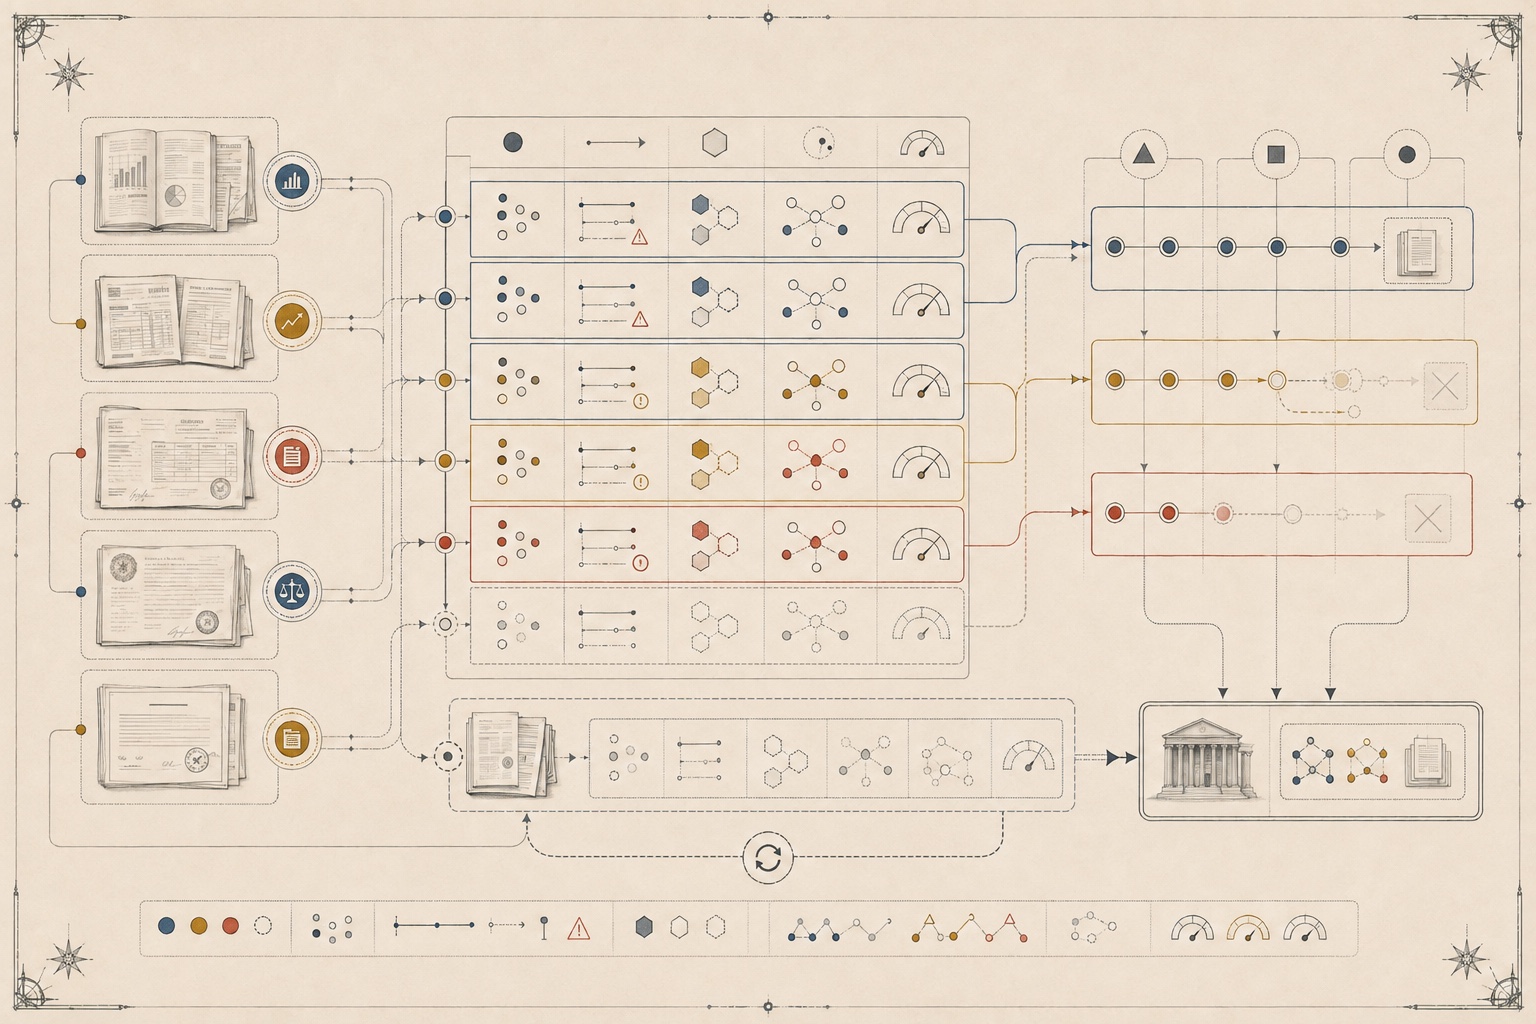
These original editorial plates are analytical aids, not source evidence or documentary reconstructions. They show what is being compared, where uncertainty sits and what observation would require the account to change.
The case in plain language
Start with the question,
not the answer.
A single disclosure or final legal event cannot explain the sequence. The relationships among information, obligations, authority, time and stakeholder understanding matter.
The method, step by step
Four moves.
One visible chain.
Symbiain keeps the moves separate: establish what is observed, relate the conditions, test the possible reading, and state what would require revision.
- 01 / Observe
What can we responsibly say?
Steinhoff’s January 2023 annual-report release identified material Group Services debt maturities due on 30 June 2023. In 2023, shareholders approved dissolution and the liquidators later confirmed that Steinhoff International Holdings N.V. and its shares ceased to exist on 13 October 2023.
- 02 / Relate
What may connect?
A financial crisis becomes more consequential when reporting uncertainty, refinancing pressure, legal process, ownership structure and time converge. The visible end-state is not a complete explanation of the system that produced it.
- 03 / Test
What would distinguish the readings?
At which points did the relationship between reported position, funding obligations, governance, creditor rights and stakeholder understanding become most fragile—and what evidence would distinguish a signal from a confirmed fact?
- 04 / Revise
What would change the account?
Revise the account whenever primary documents alter the sequence, obligation, authority or status assigned to an event.
Why use Symbiain here?
From method
to practical value.
The insight is what becomes visible. The feature is what the method does. The benefit is what the user gains. The value is what can improve in the topic at hand.
- 01
Insight
Corporate failure emerges through converging pressures, not one headline event.
- 02
Feature
Reconstructs the relationships among reporting, debt, governance, legal process, time and stakeholder exposure.
- 03
Benefit
Separates early signals, confirmed events and hindsight explanations.
- 04
Value
Creates clearer governance lessons and sharper warning questions without assigning unsupported responsibility.
What to examine
Five conditions
to hold together.
- 01Quality and timeliness of financial reporting
- 02Debt maturity, refinancing and creditor terms
- 03Governance, oversight and accountability
- 04Legal process, settlements and restructuring
- 05Stakeholder exposure and information asymmetry
Tensions to hold
Disclosure ↔ comprehension
Short-term liquidity ↔ long-term viability
Formal process ↔ stakeholder consequence
Important boundary
Public-source analytical case only. It is not an audit, forensic investigation, legal opinion, investment research, credit assessment or statement of responsibility for any person or organisation. It does not substitute for the underlying reports, court material or regulated advice.
Sources & method
Sources support the stated observations only. All analytical readings remain provisional and should be tested against a defined purpose, scope and evidence base.